Hello
Welcome
Welcome to our page. Take a moment to explore and learn more about our services. We hope you find the information you need, and we look forward to hearing from you.
For a free consultation, please email us.
Who i am?
"Empower Your Finances, Secure Your Future: Protect What Matters Most."
As a retired federal employee, I've dedicated my post-career life to serving others. As an independent Life Insurance and Health Agent, risk analyst, Medicare advisor, and small business retirement consultant, I help individuals, families, and business owners make informed decisions about their financial futures and health coverage.
I have extensive experience with federal benefits (including TSP, OPM, FEGLI, SGLI, VGLI, the Florida Retirement System, Puerto Rico Plan 106, and 403(b) plans), private-sector plans such as 401(k)s, and small business plans including 412(e)(3). I also guide beneficiaries through their Medicare and health insurance options so they can choose the coverage that best fits their needs and goals.

Retirement Benefits Education: TSP, FEGLI, 401(k), More
Thrift Savings Plan
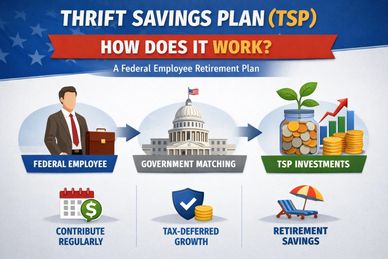
VJ Financials specializes in helping federal employees get the most out of their Thrift Savings Plan (TSP) by showing you how to maximize contributions and match, choose investments that fit your career stage, and then protect and position those funds as you approach retirement, so that when you decide to leave federal service you have a clear strategy for preserving your TSP, managing risk, and turning your balance into reliable retirement income tailored to your goals.
Office of Personnel Management (OPM)
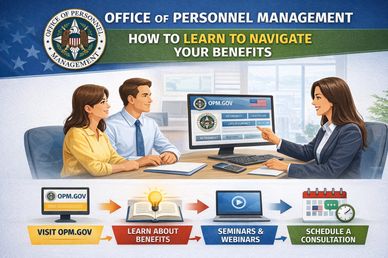
VJ Financials specializes in helping federal employees turn complex benefits into a clear, confident retirement plan by coordinating your FERS/CSRS pension, TSP, Social Security, and survivor options in plain language so you can avoid costly mistakes and maximize lifetime income—if you’ve ever wondered, “Am I really on track to retire?” we invite you to connect with us for a no‑obligation review tailored specifically to your federal career.
Unlocking Retirement Power for Small Business Owners with 412(e)(3) Plans
A 412(e)(3) plan is a fully insured defined benefit retirement plan that allows small business owners to make large, tax-deductible contributions while providing guaranteed, contract-based retirement income. Funded exclusively with fixed annuities and/or life insurance, this mechanism can help closely held businesses accelerate retirement savings, stabilize benefits regardless of market swings, and potentially improve current tax efficiency—especially valuable for owners who are older, highly compensated, or catching up on retirement planning.
The Federal Employees’ Group Life Insurance (FEGLI)

Federal Employees’ Group Life Insurance (FEGLI) is a valuable benefit, but as you age and move into retirement, your coverage typically goes down while your premiums go up. This means you can end up paying more over time for less protection, which can strain a fixed retirement income. Reviewing FEGLI before retirement helps you understand how your coverage will shrink, how your costs will rise in future age bands, and whether you should keep, reduce, or replace part of this coverage so your family is properly protected.
Servicemembers’ Group Life Insurance (SGLI)
Servicemembers’ Group Life Insurance (SGLI)
Servicemembers’ Group Life Insurance (SGLI) is low‑cost term life insurance that protects your family financially while you are in the military, but it does not last forever. As you approach retirement or separation, it is crucial to review your SGLI to understand when it ends, whether the current amount of coverage is enough for your family’s needs, and what your options are for converting it to Veterans’ Group Life Insurance (VGLI) or a private policy. Doing this before you retire helps you avoid any gap in protection, lock in coverage while you are still eligible for favorable conversion rules, and ensure your beneficiaries and coverage match your overall retirement and estate plans.